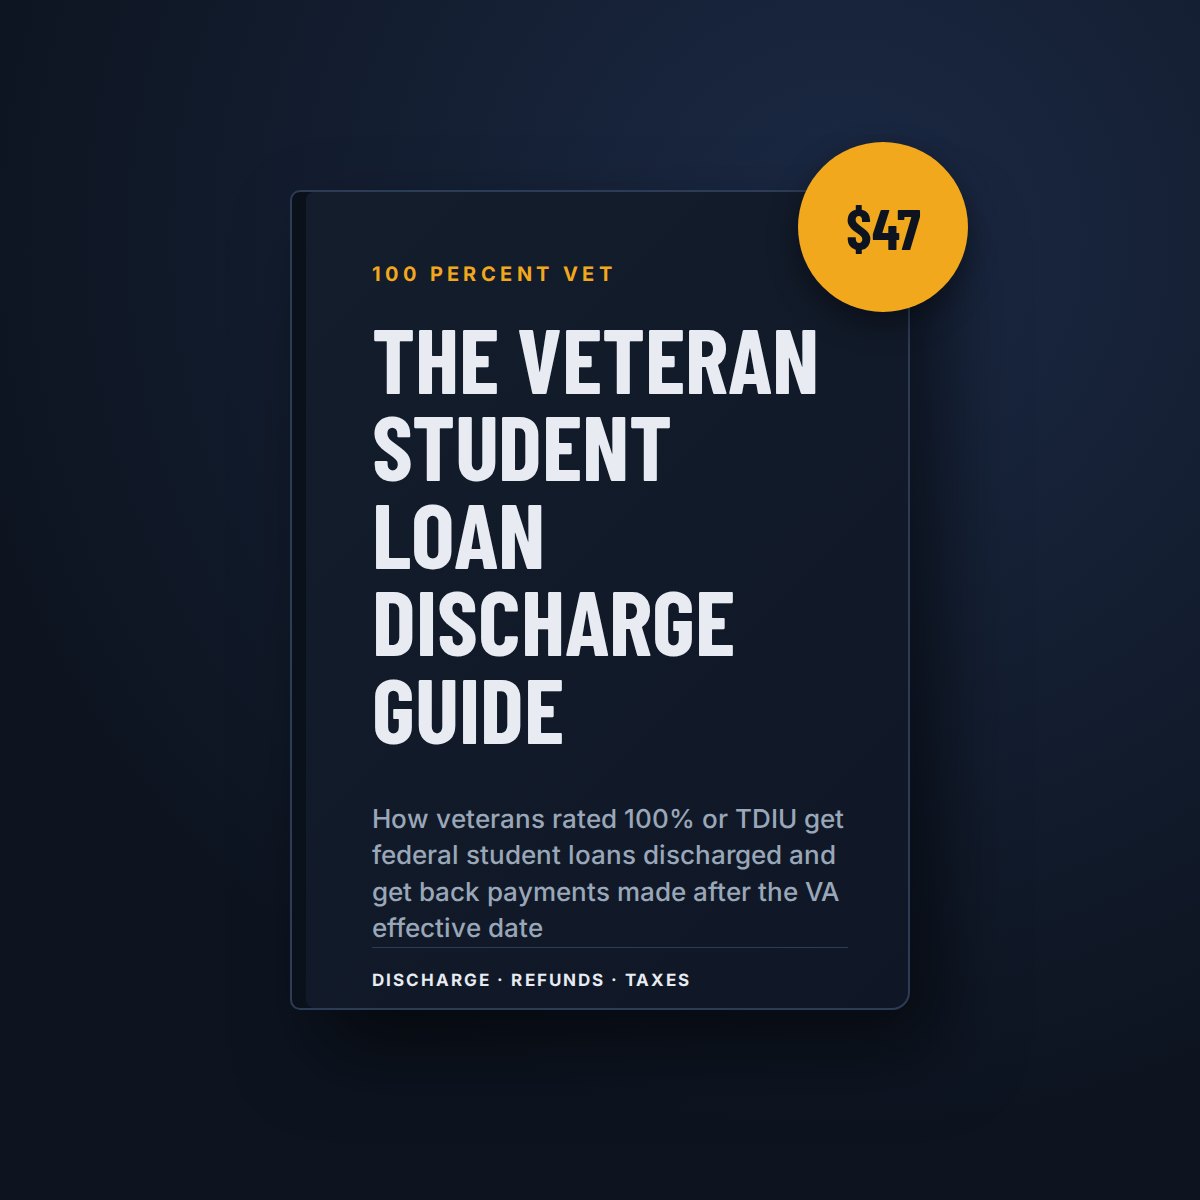
Description
If VA rates you 100% or TDIU, federal law lets the Department of Education wipe out your federal student loans through a Total and Permanent Disability (TPD) discharge. Most qualifying veterans get it automatically. Many do not, because of an old address, a missed letter or a loan the match never reached.
The Veteran Student Loan Discharge Guide is a 19-page PDF, delivered instantly after checkout. It shows how student loan discharge for veterans works, how to apply yourself when it does not happen, how to get back payments made after your VA effective date, and how to avoid the tax and credit traps.
What's inside
- Part 1, Do you qualify: what you need and what you do not (a 100% rating or TDIU, and no P&T label required), plus which loans are covered and which are not
- Part 2, the automatic discharge: how the data match works, why opting out is usually a mistake, what can go wrong, and how to check where you stand
- Part 3, apply yourself: four steps, from getting your VA letter to following up
- Part 4, get your money back: payments made on or after your VA effective date, including offsets
- Part 5, taxes: federal treatment, state rules, and what to do about a Form 1099-C
- Part 6, private loans, Parent PLUS, joint spousal consolidation loans, going back to school and PSLF
- Part 7, an 11-step checklist, and a one-page quick reference
Who this guide is for
- Veterans with federal student loans or a TEACH Grant service obligation who are rated 100% or TDIU, or expect that decision soon
- Veterans who took out a Parent PLUS loan for a child
- Veterans whose loans still show a balance after a 100% or TDIU decision
How to use it
- Confirm your rating and write down the effective date from your decision letter.
- Download your VA Benefit Summary Letter, then list every federal loan, servicer and balance at StudentAid.gov.
- Update your address with every servicer and wait for the automatic notice. If nothing happens in a few months, file the TPD application using the steps in Part 3.
- Pull your payment history, add up payments on or after the effective date, and compare it to your refund.
- Check your credit reports and keep every discharge letter with your tax records.
To learn how the ratings that qualify work, see the 100 percent VA rating, TDIU and the full list of 100 percent VA disability benefits.
Common questions
Do I need permanent and total status for a TPD discharge?
No. The Department of Education's VA option asks for a 100% disabling rating or TDIU, and it does not require the P&T label. An 80% or 90% rating does not qualify by itself.
Do I pay anyone to file the discharge?
No. You never need to pay anyone for a TPD discharge. Anyone charging a fee to file it for you is selling something the government already provides at no cost.
Are private student loans covered?
No. The federal discharge does not touch private loans. Part 6 gives you the questions to ask each private lender about its own disability policy. The guide does not guarantee any discharge or outcome.
Reviews
There are no reviews yet.